
I think it is safe to say if you have an mortgage rates at the moment, you probably know where this is going.
With the news yesterday about the average rate for first time buyers now hitting 6% for the first time in 3 years it might not come as a surprise that rates are increasing. However…
I feel like the news is a little misleading and it does not tally with what we are seeing. As the reason I started these threads was to put a real life brokers spin on the news, which can try to sensationalise things this months post should be quite interesting I think.
What mortgage rates we are looking at?
As ever, we always look at the same 4 scenarios for some consistency. The 4 scenarios are:
- 2 year deal at 90% LTV with a £999(ish) fee.
- 5 year deal at 90% LTV with a £999(ish) fee.
- 2 year deal at 85% LTV with a £999(ish) fee for adverse*
- 5 year deal at 85% LTV with a £999(ish) fee for adverse*
*Adverse in these examples is someone with 5 defaults from 2 years ago. Enough to mean we cant go to the high street.
Some of these lenders would not have actually accepted the adverse, some only lend in certain areas and some have large fees. When we put the rates below, we go with the ones we know are likely to accept the majority of people. That means there may actually be lower rates available on the market.
What mortgage rates are available now?
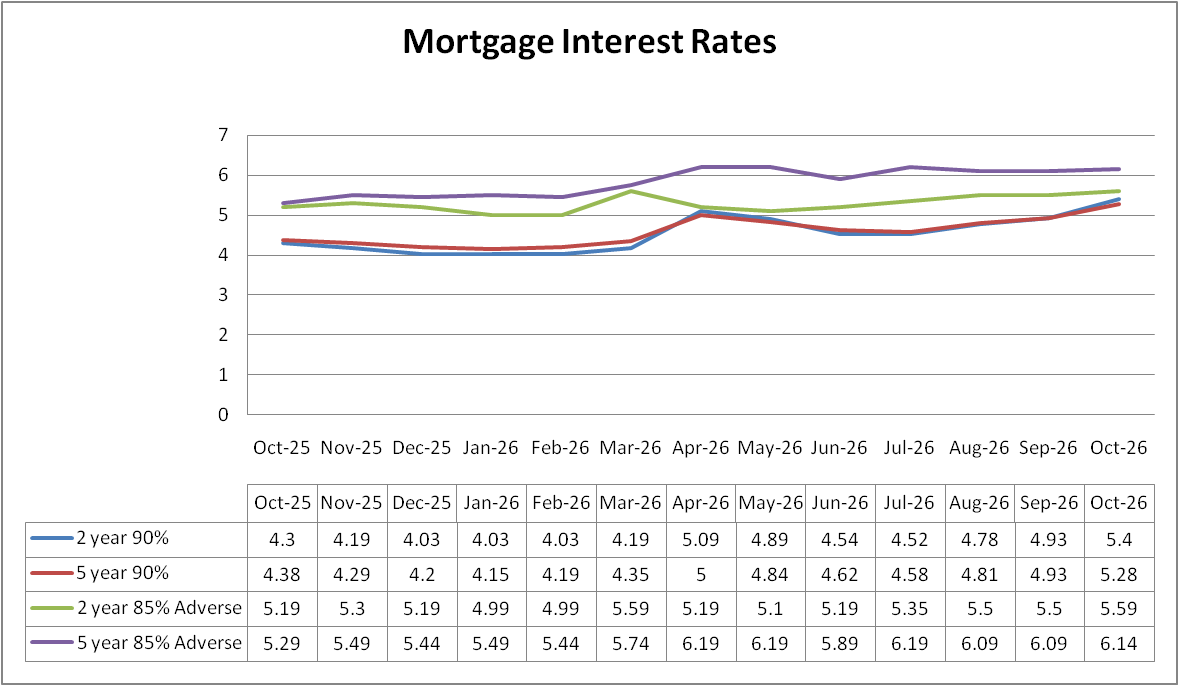
So the first thing you can see is that 3 of the 4 are well below 6%.
Now obviously that news was more specifically about first time buyers where as this is more generic. But I think it is important to say that the 6% is probably at 95% LTV and so they are working on the basis that most first time buyers will have a 5% deposit where as we have assumed 10%. There is a reason we use these figures – it is because we tend to find that most people do have 10% deposit (or more).
We are a more northern broker so that skews the customers we get but even when we do get customers from London/Brighton etc there is a big difference in deposit amounts. Some will of course have the minimum but many do have gifts from parents or inheritance.
But it is hard to dent that rates are on their way up. The gap between high street and specialist lending is closing, although this will likely be short lived and either high street rates will start to come down again or when the specialist lenders refinance their mortgage books they will have to increase their rates.
But I think it is very important to say that average rates are currently nowhere near 6% and it is only a very small part of the market which is looking at 6%. Most people are currently falling between around 4.7% and 5.5%.
Mortgage rates in 2026
Rates are currently on an upward trend. We did receive a couple of emails on Monday from lenders who were lowering their rates. However those lenders were generally out of sync with the market and so were just moving more in line with the market to get a little more business – they were not leading the charge for lower rates overall im afraid.
Summary
Last month we said “current trends suggest that rates will soon approach those previous highs once again.” and this appears to still be the case.
However, as ever we will keep an eye on the market and give you a view that we see from real life customers without trying to sensationalise anything.