
If you have previously fallen behind on a bill or credit agreement, you might be worried that homeownership is off the table. However, finding a mortgage with missed payments in the UK is a challenge many face, and it certainly does not mean your dreams of buying a home are over. While high-street banks may rely on automated scoring systems that often reject applications at the first hurdle, there are many alternative paths available.
At Mortgage Success, we specialise in helping individuals navigate adverse credit. By working with a Whole of Market broker, you gain access to specialist lenders who look beyond a computer-generated number to understand your unique financial story.
How Lenders View Missed Payments
When you apply for a mortgage, lenders assess your ‘risk.’ They want to know if you are a reliable borrower. It is important to understand how they differentiate between applicants:
- The One-Off Blip: A single missed payment from two years ago is viewed very differently than a recent string of defaults.
- Type of Credit: Lenders often distinguish between utility bill arrears (like mobile phone contracts) and serious mortgage or loan arrears.
- The Recency Factor: Credit history is chronological. Generally, the older the missed payment, the less impact it has on your current eligibility.
- Underwriting Logic: Lenders use your credit report to build a picture. They are looking for trends—does your file show a history of financial mismanagement, or was there a temporary period of life stress?
Factors That Influence Your Mortgage Eligibility
Your ability to secure a mortgage depends on more than just your credit report. Lenders will evaluate your application based on several key metrics:
- Frequency and Volume: A high volume of missed payments over a short period suggests ongoing financial difficulty.
- Account Status: Are those accounts now settled and what status did they go to? Lenders are generally more comfortable with settled arrears than those that remain outstanding. There is more on the statuses below.
- Loan-to-Value (LTV): If you have a larger deposit, you are a lower risk to the lender. This can sometimes offset credit history concerns.
- Current Affordability: Regardless of your past, you must prove you can comfortably manage the monthly mortgage repayments today. Lenders will stress-test your income against current interest rates.
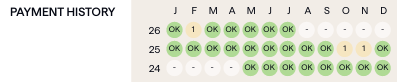
Here is how late or missed payments will be reflected on your credit report. The first image has 3 late payments, but they are all “Status 1” – this means the payment might have been paid late or missed, but it was brought up to date by the time the next payment was due.
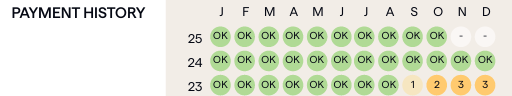
The second image shows 4 missed payments, this is where a payment was missed, so were the next 3. This would generally be treated more harshly by lenders than the multiple status 1s.
Why Specialist Lenders May Be Your Best Option
High-street lenders use credit scoring to filter out applications they do not want. It is not perfect, but they can be fussy. If you don’t fit their pre-defined scoring it becomes a case of “computer says no” and you are automatically declined. This is where specialist lenders excel.
These lenders take a manual, ‘common sense’ approach to underwriting. Instead of relying on a computer score, a human underwriter reviews your specific file. They want to hear the ‘why’ behind the missed payments. As a Whole of Market broker, we can present your case to these lenders, highlighting your current stability and long-term financial recovery. This often provides access to rates and products that simply aren’t advertised to the general public.
Steps to Take Before You Apply
Preparation is the secret to a successful application. Before you start the process, consider these steps:
- Check Your Credit Report: Use a service like CheckMyFile to see what the lenders see. Ensure all data is accurate; if you find a mistake, challenge it immediately.
- Pause New Applications: Every application leaves a footprint. Avoid applying for further credit or loans while preparing for a mortgage.
- Gather Evidence: If your missed payments were caused by a specific event (e.g., redundancy, illness, or a relationship breakdown), keep documentation. This can be vital for your broker when building your ‘story.’
- Seek Expert Advice: Don’t apply to multiple lenders yourself. Every ‘hard search’ on your file can further damage your score. Speak to an independent broker first to assess which lenders fit your profile.
How Mortgage Success Can Help
Navigating the mortgage market with a history of missed payments can feel overwhelming, but you don’t have to do it alone. As an independent, Whole of Market broker based in Manchester and serving clients across the UK, we have access to over 70 lenders, including those who specialise in adverse credit cases.
We don’t rely on automated scoring. We look at your individual circumstances and fight your corner. Whether you are a first-time buyer or looking to remortgage, our goal is to find you a solution that works for your long-term future.
Ready to take the next step? Contact us today for a confidential, free consultation to discuss your situation. We have years of experience with these types of applications.